Unlocking Opportunity: Navigating the New Legal FICO Credit File Landscape
In recent years, the landscape of credit reporting has undergone significant transformation, particularly with the introduction of a new FICO credit file. This change represents more than just a shift in metrics; it opens doors to a myriad of opportunities for consumers and lenders alike. As financial institutions increasingly rely on advanced algorithms and updated scoring models, understanding the nuances of the new credit file is essential for anyone looking to navigate their financial journey effectively.
For individuals seeking to improve their credit profiles, the new legal FICO credit file offers fresh insights and strategies. With updated criteria that reflect modern financial behaviors, consumers may find that their creditworthiness is evaluated in a more favorable light. This article aims to explore what the new credit file entails, how it differs from previous models, and the potential implications for borrowers striving to unlock new opportunities in their financial lives.
Understanding the New Legal FICO Credit File
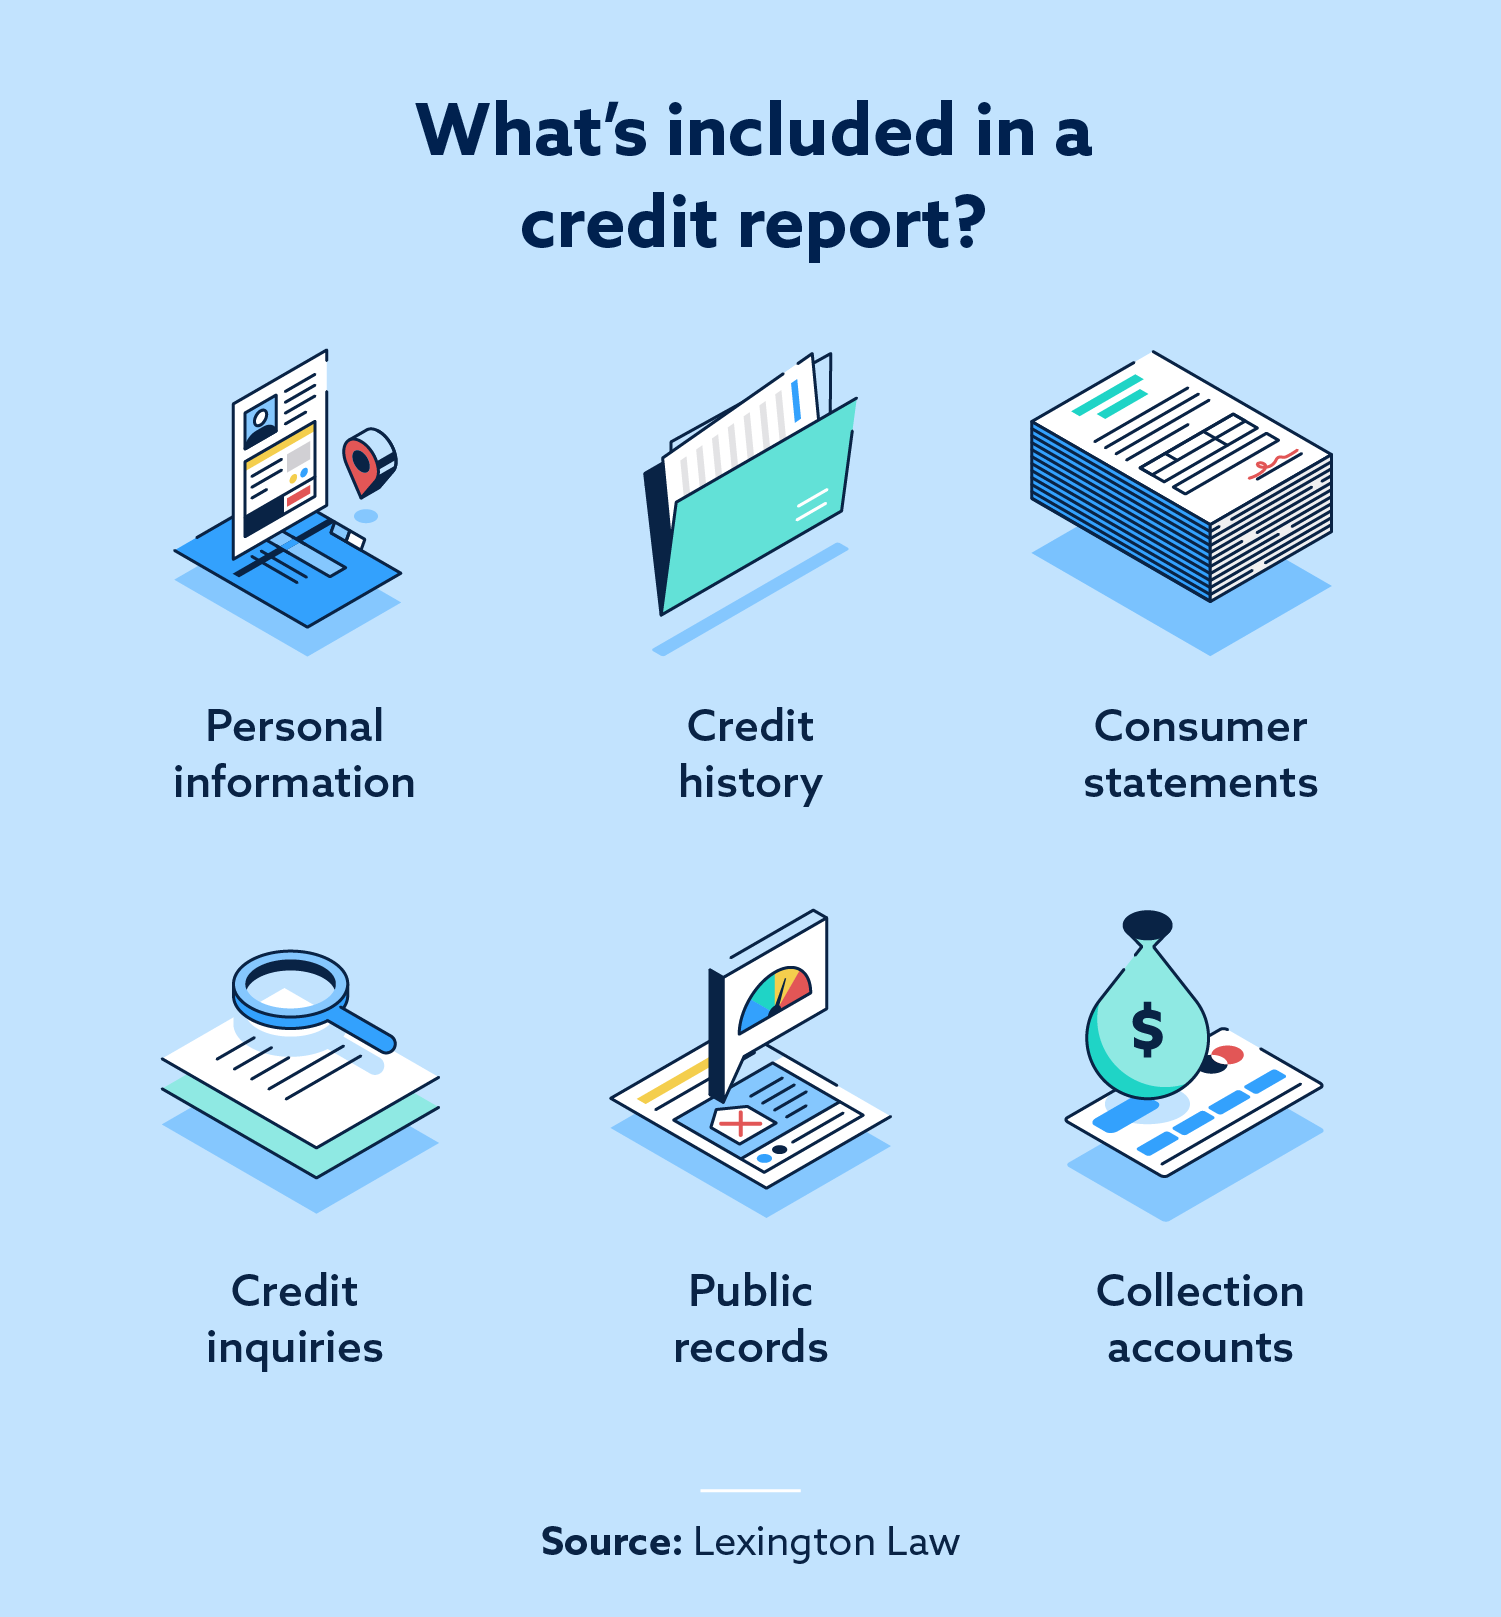
The new legal FICO credit file represents a significant shift in how credit reporting will be conducted and understood by consumers and lenders alike. This system is designed to provide a more accurate reflection of an individual's creditworthiness, taking into account not only traditional credit history but also additional factors that may impact a consumer's financial behavior. The introduction of this framework aims to promote greater transparency and fairness within the credit landscape, especially for those who may have been historically underserved.
At the heart of this new structure is the emphasis on consumer rights and the ability to contest and correct inaccuracies within credit reports. Consumers will have improved access to their credit files, allowing them to see firsthand what data is being reported and how it influences their credit scores. This empowerment is crucial, as it enables individuals to take proactive steps towards managing their credit health and ensuring that they are not unfairly penalized for errors that can easily occur.
Moreover, the new legal FICO credit file is anticipated to foster innovation among lenders and the credit industry at large. With additional data points available for assessment, lenders can develop more tailored solutions and credit products that meet the specific needs of a diverse consumer base. This evolution not only aims to enhance individual financial opportunities but also to stimulate broader economic growth by enabling a wider spectrum of consumers to access credit.
Implications for Consumers and Lenders
The introduction of the new FICO credit file system presents significant implications for consumers. With the ability to leverage alternative data sources, consumers who previously struggled to establish a credit history can now gain access to credit opportunities. This change may empower a broader demographic, including those with limited credit histories, thereby expanding financial inclusion. As a result, many individuals may find themselves eligible for loans, credit cards, and other financial products that were previously out of reach.
For lenders, the new credit file offers both challenges and opportunities. By incorporating alternative data, lenders can refine their risk assessment processes and make more informed lending decisions. This might lead to a competitive advantage for those willing to embrace the new technology and methodologies. However, lenders must also be cautious about the integration of this data, ensuring they remain compliant with regulations and uphold fair lending practices.
Overall, the evolution of the credit file landscape may force both consumers and lenders to adapt. Consumers will need to become more educated about their credit profiles and how new data points can influence their scores. Lenders, on the other hand, may need to invest in training and technology to effectively harness this new data, maintaining their operational accuracy while catering to a diverse clientele.
Strategies for Optimizing Credit Opportunities
To maximize the potential of the new credit file system, individuals should focus on building and maintaining a positive credit history. This starts with timely payments on existing debts, as payment history is a vital factor in credit scoring. Setting reminders for due dates or utilizing automatic payments can help ensure that bills are paid on time. Additionally, consumers should be mindful of their credit utilization rate, aiming to keep balances low relative to their credit limits. This not only reflects responsible credit management but also enhances the overall credit profile.
Furthermore, it is essential to understand the types of credit accounts being reported in the new FICO credit file. Diversifying credit types, such as combining revolving credit accounts with installment loans, can improve credit scores. Consumers should also consider seeking credit products that are specifically designed to support credit building, such as secured credit cards or credit-builder loans. By consciously choosing credit products that report to the new FICO system, individuals can strategically enhance their credit profile.
Lastly, staying informed about the evolving landscape of credit reporting is critical. Regularly checking credit reports for errors or outdated information can prevent negative impacts on credit scores. Individuals should also take advantage of educational resources and tools provided by credit bureaus and financial institutions. Engaging with financial literacy initiatives can empower consumers to make informed decisions regarding their credit and uncover new opportunities within the new credit file framework.
Public Last updated: 2024-08-03 01:29:55 AM